PHOENIX – October 29, 2026 -- Honeywell Aerospace (Nasdaq: HONA) raised its full-year 2026 pro forma standalone adjusted earnings per share and second-half free cash flow guidance after third-quarter sales rose 2% to $4.6 billion, and its board declared an inaugural quarterly dividend of $0.40 per share.
Net income came to $0.7 billion. Adjusted EBIT rose 1% to $1.2 billion, even with new costs of operating as an independent public company and a net benefit of about $50 million from International Emergency Economic Powers Act (IEEPA) tariff refunds. The company kept its full-year organic sales outlook and narrowed its adjusted EBIT guidance range.
Dividend is payable December 4 to holders of record on November 13
The board approved the $0.40 cash dividend as the first since the company's separation from Honeywell International. CEO Jim Currier tied the payout to visibility into free cash flow growth. He said the company aims to pay a competitive, growing dividend while keeping financial flexibility and a strong investment-grade credit rating.
Backlog climbs 12% to $19.3 billion as defense orders lead
Trailing twelve-month orders rose 9%, led by Defense and Space. Year to date, Honeywell Aerospace has secured more than $20 billion in new wins at estimated lifetime value. They include over $2 billion in awards for navigation and RF systems on missile and munitions programs, some on platforms prioritized by the Munitions Acceleration Council.
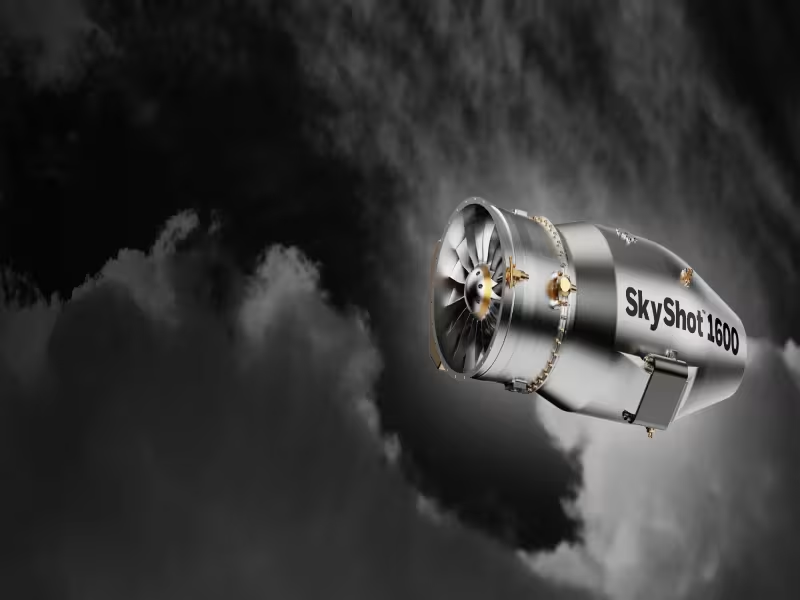
The U.S. Air Force also advanced the company's SkyShot 1600 engine into Preliminary Design Review under its Autonomous Collaborative Platform program. The engine is designed for collaborative combat aircraft and unmanned aircraft systems.
Commercial Original Equipment sales rise 7% while aftermarket growth stalls at 2%
Commercial Original Equipment sales reached $0.7 billion, up 7% reported and 8% organic, on higher air transport build rates and selectable equipment volumes. Commercial Aftermarket sales of $2.1 billion grew 2%. Demand was healthy, but mechanical component availability limited growth.
Defense and Space sales rose 1% to $1.8 billion. Growth led by the CAES and Civitanavi acquisitions was partly offset by lower international volumes from supply constraints and the wind-down of a non-aerospace restricted government program.
Engines and Power Systems segment EBIT falls 16% on mix and cost
Segment results diverged:
- Electronic Solutions sales grew 4% reported and 5% organic. Segment adjusted EBIT rose 11% as tariff refunds and pricing outweighed unfavorable mix and higher costs.
- Engines and Power Systems sales increased 3% reported and 2% organic on higher Commercial Aftermarket volumes. Segment adjusted EBIT fell 16% as unfavorable mix and higher costs outweighed price and tariff refunds.
- Control Systems sales were flat. Defense and Space growth was offset by a Commercial Aftermarket decline, while segment adjusted EBIT rose 2% on price.
Supplier bottlenecks limit output as Tempe plant expands by 300,000 square feet
Currier said a small number of mechanical suppliers are limiting output growth. He cited encouraging signs from these pacing suppliers and ongoing qualification of additional material sources as the basis for higher sales and output growth in 2027 and beyond. The company detailed root causes and corrective actions at a September investor conference.
Honeywell Aerospace also announced a 300,000-square-foot expansion of its Tempe, Arizona manufacturing facility, expected to open in late 2028. It will add capacity, lean manufacturing, automation and supply-chain resilience for Control Systems production and next-generation platforms.
Separately, the City of Phoenix Aviation Department signed an agreement to study adapting the company's Surface Alert (SURF-A) technology for ground vehicle operators at three local airports, including Phoenix Sky Harbor International.