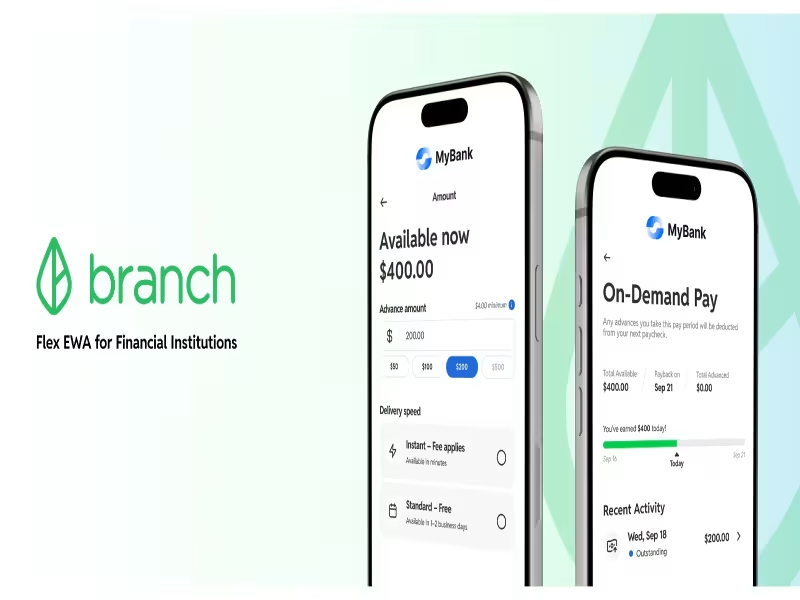
Tampa – October 14, 2026 -- Branch has launched a white-label Flex earned wage access (EWA) model for banks and credit unions that carries no balance-sheet risk and requires no new underwriting, because Branch funds every advance.
The configuration lets financial institutions embed EWA inside their own banking apps under their own brand. Branch oversees compliance and handles integrations, calculations, disbursement and repayment through an API-first, bank-grade compliant integration.
Branch extends its Flex model from employers to financial institutions
The launch builds on the Flex model Branch introduced earlier this year, which made embedded EWA faster and lighter to deploy for employers. The same approach now targets banks and credit unions facing the multi-year timelines typical of core banking projects.
Institutions can go live through a 60-day sprint
Branch says an institution can launch in a 60-day sprint covering technical integration, testing and certification, and go-live. The company draws on a number of employer payroll connections out of the box.
Depositors choose when to receive their pay. An instant transfer to an existing debit card carries a small fee, while standard delivery is free. Most instant transfers complete within 30 minutes, though service disruptions or connection issues can cause delays.
Branch pitches EWA as a deposit-retention and fee-income tool
Branch data shows an EWA depositor is more engaged than a typical depositor, with stickier deposits and higher card activity. The company says neobanks and digital-first challengers have used EWA to win primary deposit relationships. For banks and credit unions, it says Flex EWA offers a way to compete for new customers, deepen existing relationships and generate non-interest income.
Branch founder and CEO Atif Siddiqi said people increasingly expect EWA from the institutions they already bank with, and that the offering lets banks meet that demand under their own brand.
Financial institution model joins Core and Flex EWA in one system
The financial institution configuration joins Branch's Core and Flex EWA models. Companies, platforms, and now banks and credit unions can deliver EWA through a single system rather than stitching together point solutions.
Branch also supports paycard and direct deposit, cashless tips and mileage, 1099 contractor payouts, W-2 employee payments and embedded finance. Partners can start with one use case and add others as needs grow.
Branch is not a bank. It acts as technology service provider and program manager for Lead Bank, Member FDIC, which provides the banking services, including money transmission, needed to deliver EWA. Flex EWA is available now to banks and credit unions.